How to Buy Land With Owner Financing: A Complete Step-by-Step Guide

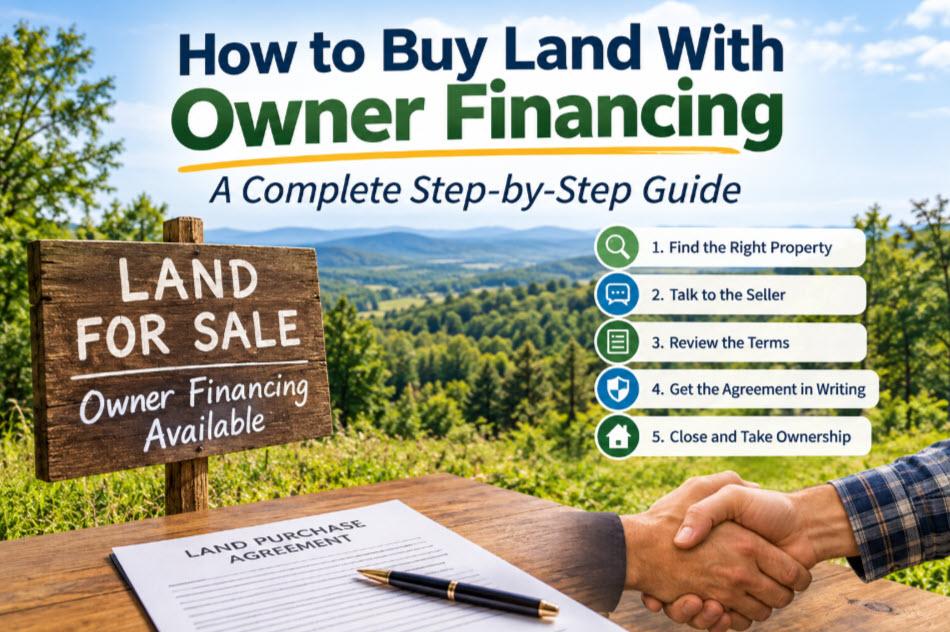
Buying land can be an exciting way to secure a homesite, build your future property, create a recreational retreat, or simply own a piece of real estate. With options like owner financing, purchasing vacant land can become more accessible, especially for buyers who may find traditional bank financing more challenging than financing a home.
That is where owner financing—also called seller financing—can provide another option.
With owner financing, the seller agrees to let the buyer pay for the property over time instead of requiring the buyer to obtain a traditional loan from a bank. Depending on the agreement, the buyer may make a down payment followed by monthly payments until the agreed balance is paid.
However, owner financing is still a real estate transaction, and buyers should understand exactly what they are agreeing to before making a payment.
This guide explains how to buy land with owner financing, what to investigate before purchasing, how payments work, what documents may be involved, and what questions you should ask the seller.
Important: Owner-financing laws and requirements vary by state and by the type of property and transaction. This article is for general educational purposes and is not legal or tax advice. Consider speaking with a qualified real estate attorney, title company, or tax professional before entering into an agreement.
What Is Owner Financing?
Owner financing is a real estate transaction in which the property seller provides financing to the buyer rather than requiring the buyer to obtain all of the purchase money from a traditional lender.
For example, imagine a parcel of land is offered for $20,000.
Instead of paying the entire $20,000 in cash, the seller might agree to:
- Purchase price: $20,000
- Down payment: $4,000
- Amount financed: $16,000
- Monthly payment: An agreed amount
- Term: An agreed number of months or years
- Interest: An agreed rate, if applicable
The exact terms depend on the seller and the written agreement.
The IRS recognizes installment sales as transactions where the seller receives at least one payment after the tax year of the sale. An installment obligation can involve a note, deed of trust, land contract, or another form of evidence of the buyer’s debt.
Owner Financing vs. a Traditional Land Loan
With traditional financing, a bank or other lender provides the money needed to purchase the property. The buyer then makes payments to that lender.
With owner financing, the seller is providing the financing arrangement.
This can potentially make the process more accessible for buyers who don’t want to go through a traditional lender, but it does not mean the buyer should skip due diligence.
A seller-financed transaction can still involve:
- A purchase agreement
- Promissory note
- Deed
- Mortgage or deed of trust
- Land contract or installment contract
- Title work
- Recording
- Closing costs
- Property taxes
- Insurance, where applicable
The exact documents depend on the transaction and state law.
How to Buy Land With Owner Financing: Step by Step
Step 1: Find Land That Fits Your Needs
Start by determining what you’re actually looking for.
Consider:
- Location
- Acreage
- Price
- Road access
- Utilities
- Zoning
- Restrictions
- Property taxes
- Terrain
- Flood zones
- Wetlands
- Septic feasibility
- Water availability
- Intended use
Your intended use is particularly important.
For example, someone looking for land to build a home may have very different requirements from someone looking for recreational land, agricultural property, or a place for a future cabin.
Don’t choose a parcel simply because the monthly payment looks affordable. The land itself needs to work for your intended purpose.
Step 2: Ask Whether the Seller Offers Owner Financing
Not every land seller offers financing.
If a property interests you, ask:
“Do you offer owner financing, and what are the terms?”
You should request the complete financing terms rather than focusing only on the monthly payment.
Ask about:
- Purchase price
- Down payment
- Interest rate
- Monthly payment
- Number of payments
- Total amount financed
- Due date
- Late-payment policy
- Early payoff policy
- Closing costs
- Whether there is a balloon payment
- When the deed transfers
- What happens if a payment is missed
A low monthly payment can sometimes result from a very long repayment period, so it’s important to understand the total cost.
Step 3: Visit the Property
Whenever possible, visit the land before purchasing it.
Look at:
- Road conditions
- Property access
- Surrounding properties
- Terrain
- Drainage
- Vegetation
- Nearby development
- Utility infrastructure
- Signs of flooding
- Boundaries and landmarks
A map can help you locate the parcel, but a map is not necessarily a substitute for physically inspecting the property.
If you cannot visit yourself, consider having someone you trust inspect it or obtain professional assistance.
Step 4: Verify the Property Information
Before signing an agreement, independently verify important property details.
Depending on the property, this can include:
Property boundaries
Find out where the parcel begins and ends. If you need precise boundary locations, ask whether a recent survey is available and determine whether a professional survey is appropriate.
Legal access
Don’t assume that a visible road automatically means you have legal access to the property.
Ask how the property is accessed and whether there is recorded legal access or an easement where necessary.
Zoning and permitted use
Check with the appropriate local government regarding zoning and land-use requirements.
For example, if your plan is to build a house, park an RV, place a manufactured home, or develop the property, verify that the intended use is actually permitted.
Utilities
“Utilities available” does not necessarily mean that utilities are already connected to the property.
Ask whether:
- Electricity is at the property
- Public water is available
- Sewer is available
- Natural gas is available
- A well is required
- A septic system is required
Also contact the utility providers to determine connection requirements and potential costs.
Septic suitability
If there is no public sewer, determine whether the property can support a septic system.
A property can look ideal and still have limitations because of soil, slope, wetlands, groundwater, or other site conditions.
Step 5: Research Taxes, Restrictions, and Other Costs
The purchase price is only one part of the cost of owning land.
Before buying, investigate:
- Property taxes
- HOA or POA fees
- Road-maintenance obligations
- Special assessments
- Survey costs
- Closing costs
- Title insurance
- Recording fees
- Utility connection costs
- Well costs
- Septic costs
- Clearing and grading
- Construction costs
This is especially important when buying inexpensive land.
A $10,000 parcel isn’t necessarily a $10,000 project.
For example, if your goal is to build a home, the cost of preparing the property and connecting utilities could be significant.
Step 6: Review the Owner-Financing Terms Carefully
Once you have confirmed that the land meets your needs, review the financing agreement.
A typical owner-financing arrangement may specify:
Purchase price: $25,000
Down payment: $5,000
Financed amount: $20,000
Interest rate: As specified in the agreement
Monthly payment: As specified
Term: 60 months
These numbers are only an example. Actual terms vary.
Make sure you understand whether the monthly payment includes interest and how the balance is calculated.
Also ask whether there is a balloon payment.
A balloon payment means the buyer may have relatively smaller periodic payments but still owe a larger amount at the end of the agreed term.
Don’t assume that paying monthly automatically means the entire balance will be paid off at the end of the term.
Step 7: Understand When You Receive the Deed
One of the most important questions in an owner-financed land transaction is:
“When does the deed transfer to the buyer?”
There are different structures for seller-financed transactions.
In some arrangements, the deed transfers at closing while the seller receives a security interest in the property.
In others, such as certain contracts for deed, the seller may retain legal title until the buyer completes the required payments. The CFPB explains that contracts for deed can also be called land contracts or installment land contracts.
These structures have important legal differences.
If the deed will not transfer until the property is paid in full, make sure you understand:
- Your rights while making payments
- Your responsibilities for taxes
- Maintenance obligations
- Default provisions
- What happens after a missed payment
- Whether the contract is recorded
- What happens if the seller sells or transfers their interest
- What happens if the buyer wants to pay the balance early
Because these issues can vary significantly by state, professional legal review can be valuable.
Step 8: Use a Professional Closing Process
Whenever possible, use a reputable title company, escrow company, or real estate attorney to handle the closing.
A professional closing process can help address issues involving:
- Ownership
- Liens
- Title
- Documents
- Funds
- Recording
- Deed transfer
The CFPB describes the role of settlement agents, title companies, escrow companies, and attorneys in real estate closings and emphasizes reviewing documents before signing.
Don’t simply send a large down payment based on a text message or informal agreement.
Make sure you know who legally owns the property and that the transaction documents accurately describe the property and financing arrangement.
Step 9: Understand Your Responsibilities After Closing
Buying land doesn’t end when you make the first payment.
Depending on your agreement, you may be responsible for:
- Monthly payments
- Property taxes
- Property maintenance
- Insurance, if applicable
- HOA or POA fees
- Road-related expenses
- Utility bills
- Other property-specific obligations
Your contract should clearly explain these responsibilities.
If the seller retains legal title under a contract-for-deed arrangement, the buyer may still have responsibilities normally associated with property ownership.
Step 10: Make Your Payments on Time
Once the agreement is finalized, keep careful records of every payment.
Save:
- Payment confirmations
- Receipts
- Copies of the agreement
- Correspondence
- Tax records
- Closing documents
- Any amendments to the agreement
Set up reminders or automatic payments if the agreement permits them.
Missing payments can have serious consequences. The contract should explain what constitutes default and what happens afterward.
Before signing, make sure you understand the consequences of late or missed payments.
Can You Pay Off Owner-Financed Land Early?
Sometimes, yes.
But don’t assume.
Check the agreement for an early payoff or prepayment provision.
If you plan to pay the property off early, ask the seller or closing professional for a written payoff statement showing exactly how much is required to satisfy the obligation.
After the final payment, make sure you understand what documentation confirms that the debt has been satisfied and, where applicable, how the deed or lien documentation will be handled.
What Are the Benefits of Owner Financing?
Owner financing can have several potential advantages for land buyers.
Flexible payment structure
The seller may offer terms that differ from conventional lending.
Potentially simpler financing process
The buyer may not have to go through the same process as a traditional bank loan, depending on the transaction.
More options for vacant land
Some traditional lenders have specific requirements for vacant-land loans, while seller financing may offer another purchasing structure.
Ability to spread payments over time
Instead of paying the entire purchase price immediately, the buyer may be able to spread payments over an agreed period.
However, these potential benefits need to be weighed against the specific terms and legal structure of the transaction.
What Are the Risks?
Owner financing isn’t automatically safer or easier than traditional financing.
Potential issues can include:
- Unclear contract terms
- Higher total purchase cost
- Interest charges
- Large balloon payments
- Default consequences
- Title problems
- Property tax issues
- Unrecorded agreements
- Restrictions on how the property can be used
- Seller-related complications
The CFPB has specifically highlighted risks associated with certain contracts for deed, including situations where buyers can lose the property and accumulated payments after default.
That doesn’t mean every seller-financed land transaction has these problems. It means buyers should understand the specific agreement before signing.
What Should You Ask Before Buying Owner-Financed Land?
Before committing to a purchase, consider asking these questions:
- What is the total purchase price?
- How much is the down payment?
- What is the interest rate?
- What will my monthly payment be?
- How many payments are required?
- Is there a balloon payment?
- Can I pay the balance early?
- Are there any prepayment penalties?
- When does the deed transfer?
- Who pays property taxes?
- Who pays HOA or POA fees?
- Who is responsible for maintenance?
- Is there legal road access?
- Are there restrictions on the property?
- Is the property in a flood zone?
- Are utilities available?
- Is public water available?
- Is sewer available?
- Is a septic system possible?
- Has the property been surveyed?
- Are there liens or other title issues?
- What happens if I miss a payment?
- Who handles the closing and recording?
- What documents will I receive?
- What happens after the final payment?
Getting clear answers to these questions can help you understand the transaction before you commit.
Don’t Focus Only on the Monthly Payment
One of the biggest mistakes a buyer can make is looking only at the monthly payment.
For example, two properties could have similar monthly payments but dramatically different purchase prices, interest costs, repayment periods, or balloon-payment requirements.
Instead, look at the entire financing structure.
Compare:
Purchase price + interest + fees + closing costs + other expected property expenses
This gives you a much clearer picture of what the land may actually cost you.
Owner Financing and Taxes
Seller-financed transactions can also have tax implications.
The IRS explains that qualifying installment sales may allow sellers to recognize gain over time as payments are received rather than necessarily recognizing the entire gain in the year of sale. Interest received by the seller generally has separate tax treatment.
The tax rules can become complicated depending on:
- The seller’s basis
- Purchase price
- Interest rate
- Relationship between buyer and seller
- Type of property
- Existing debt
- Whether the property is used for business or investment
- The structure of the financing
For that reason, sellers should consult a tax professional before structuring an owner-financed sale.
Buyers should also keep copies of their purchase and financing documents for their records.
Final Thoughts: Take Your Time Before Buying
Owner financing can provide an alternative way to purchase land without using a conventional land loan. Instead of paying the entire purchase price upfront, the buyer and seller agree to a payment structure that can spread the cost over time.
But the financing arrangement is only one part of the decision.
Before buying owner-financed land, investigate the property, title, access, zoning, utilities, taxes, restrictions, financing terms, and closing documents.
Most importantly, make sure you understand exactly what happens if you make every payment—and what happens if you don’t.
A professional title company, closing attorney, real estate attorney, or tax professional can help you understand the transaction and applicable state requirements.
If you’re considering owner-financed land, remember the basic process:
Find the right property → Inspect the land → Verify the property → Review the financing terms → Perform due diligence → Use a professional closing process → Sign the documents → Make your payments → Complete the payoff and title process.
With careful research and clear documentation, buyers can approach an owner-financed land purchase with a much better understanding of both the opportunity and the obligations involved.
👉 Ready to start your land ownership journey?
Explore available properties at MrLandSeller.com and discover affordable land deals with easy owner financing.
